
VCC structure in Singapore
Choose between a standalone fund and an umbrella, then set the manager, governance and investor terms.
Three decisions define the operating model
Set the vehicle, management arrangement and investor terms together.
One fund or an umbrella?
Use a standalone VCC for one pool, or an umbrella when separate sub-funds are needed.
Who manages and oversees it?
Appoint an eligible fund manager, directors and the required officers; define provider responsibilities.
How do investors participate?
Set share classes, subscriptions, redemptions and valuation terms for the mandate.
- 01Fund mandate
- 02VCC and manager
- 03Investor and service terms
Start with the operating decision: one fund for a single mandate, or separate sub-funds under an umbrella. The VCC also needs an eligible manager, directors and service arrangements. For setup, tax and cost planning, see the VCC Singapore overview.
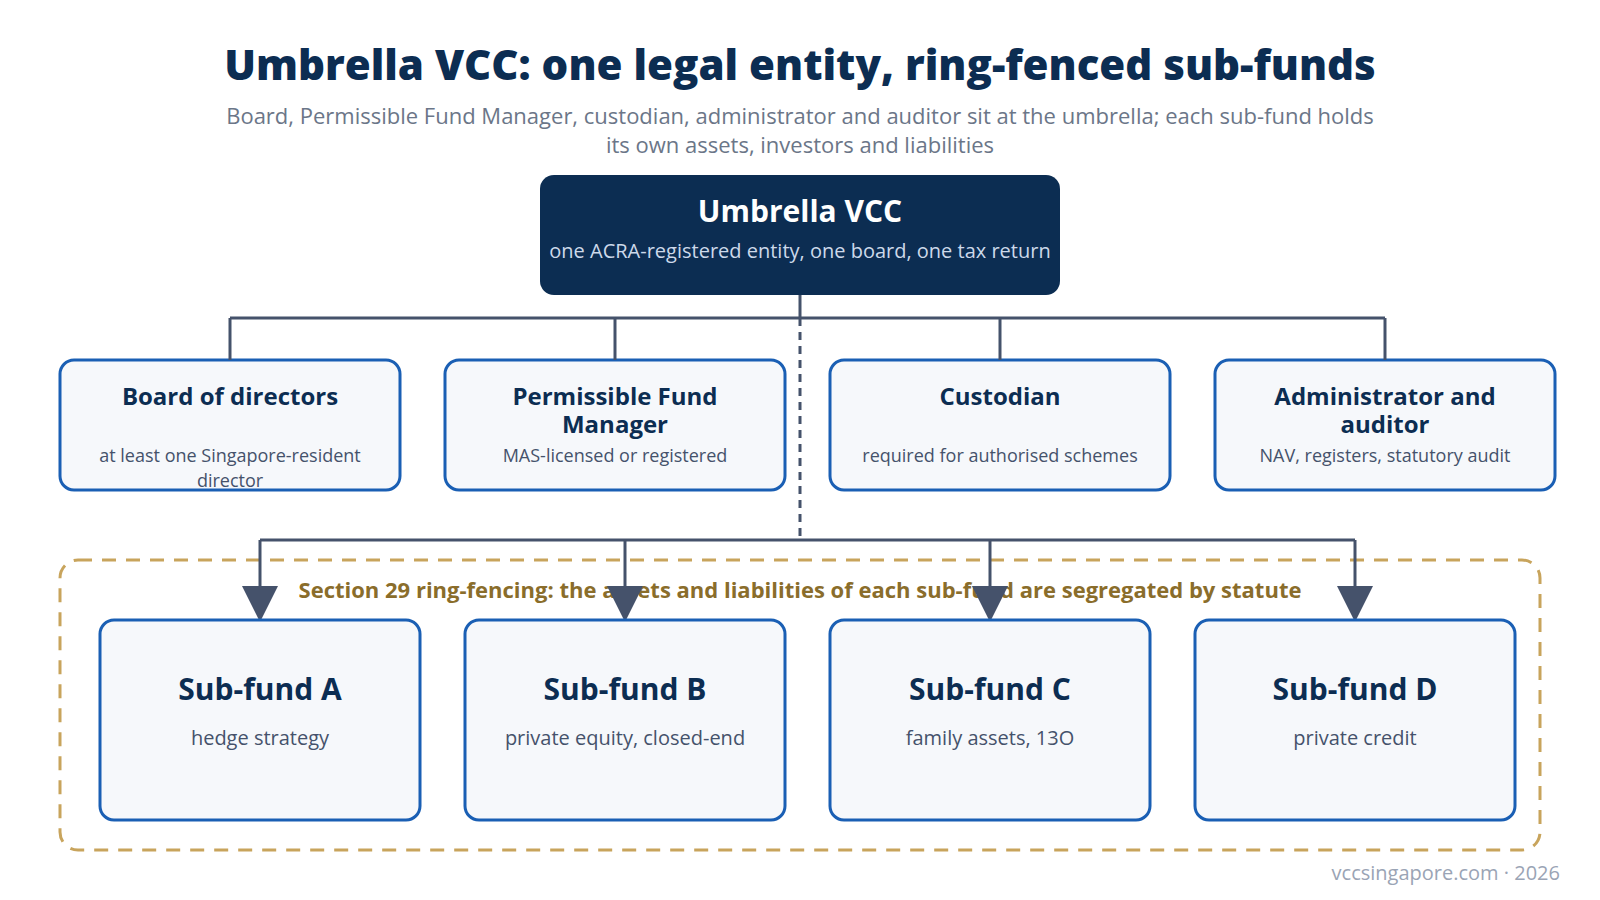
A Variable Capital Company is Singapore’s corporate fund vehicle. A standalone VCC holds one fund; an umbrella VCC contains sub-funds with segregated assets and liabilities. The VCC is the legal entity. A sub-fund is not a separate company.
Scope, definitions and conditions
A Variable Capital Company (VCC) is Singapore's purpose-built corporate fund vehicle — a company whose share capital always equals its net asset value, that can issue and redeem shares freely, and that can hold many ring-fenced sub-funds under a single legal entity. It was created under the Variable Capital Companies Act 2018 to give fund managers an onshore alternative to offshore structures like the Cayman segregated portfolio company. Unlike an ordinary private limited company, a VCC is designed from the ground up for investment funds: capital is variable, dividends can be paid out of capital, and the shareholder register is not public.
Structural requirements and sources
The reference below identifies the principal structural requirements and their sources. The following sections explain their application.
- Capital equals NAV
- A VCC’s paid-up share capital is deemed at all times to equal its net asset value. It issues and redeems shares at NAV without shareholder approval, solvency statements or a court-sanctioned capital reduction — the feature that makes it suited to open-ended funds with regular subscriptions and redemptions. Source: VCC Act 2018.
- Dividends from capital
- A VCC may pay dividends out of capital, not only out of profits, provided the directors are satisfied it is solvent. Source: VCC Act 2018.
- Standalone or umbrella
- A VCC is either a single standalone fund or an umbrella with two or more sub-funds, each with its own investment mandate, investors and asset pool, all inside one legal entity. Source: VCC Act 2018.
- Statutory ring-fencing
- Under Section 29 of the VCC Act, the assets of one sub-fund cannot be used to discharge the liabilities of another, including in insolvency; each sub-fund is wound up separately. Source: VCC Act 2018, s 29.
- Register and accounts are private
- A VCC must keep a register of members and file audited financial statements, but neither is available for public inspection on ACRA’s registry; they are provided to regulators and law-enforcement on request. Source: ACRA VCC FAQs; MAS response to feedback on the VCC framework.
- It cannot be self-managed
- Every VCC must appoint a Permissible Fund Manager: a fund management company licensed by MAS under a Capital Markets Services licence, a venture capital fund manager licensed under the simplified VCFM regime, or an exempt financial institution such as a bank. A VCC with no manager cannot be incorporated or continued. Source: VCC Act 2018; MAS.
- Board composition
- At least one director must be ordinarily resident in Singapore, and at least one director — who may be the same person — must be a director or qualified representative of the Permissible Fund Manager. Source: VCC Act 2018; ACRA.
- Local substance
- A VCC needs a registered office in Singapore, a Singapore-resident company secretary and a Singapore-based auditor, and must comply with MAS’s anti-money-laundering requirements. Source: VCC Act 2018; MAS Notice VCC-N01.
- Accounting standards
- Financial statements may be prepared under Singapore Financial Reporting Standards or IFRS; a VCC that has no authorised (retail) scheme may also use US GAAP. Source: VCC (Financial Statements) framework; ACRA.
- One tax return for the umbrella
- For income tax an umbrella VCC is a single entity and files one return, while each sub-fund’s income and losses are computed separately and ring-fenced. Source: IRAS e-Tax Guide: Tax Framework for VCCs.
- Fund incentives: 13O and 13U
- A qualifying VCC may be considered for Sections 13O or 13U on specified income from designated investments. Section 13OA is the separate limited-partnership scheme; incorporation does not confer a tax award. Source: IRAS Tax Framework for VCCs, paragraph 5.7.
- Certificate of Residence
- A VCC can apply for an IRAS Certificate of Residence if its control and management are exercised in Singapore. An umbrella VCC applies for its sub-fund; IRAS names both on the certificate. Treaty relief depends on the relevant treaty and source-jurisdiction conditions. Source: IRAS Certificate of Residence guidance.
- Inward re-domiciliation
- An eligible foreign corporate fund may transfer its registration to Singapore as a VCC without creating a new legal entity. Review contracts, investors, banking and custody separately; statutory continuity does not complete the operational move. Source: ACRA re-domiciliation guidance.
- Registered with ACRA, supervised by MAS
- ACRA incorporates and registers VCCs and sub-funds; MAS supervises the manager and the VCC’s AML/CFT obligations. MAS reported 1,406 VCCs incorporated or re-domiciled and 3,443 sub-funds by end-2025; ACRA counted 1,303 active VCCs then. Source: ACRA; MAS Asset Management Survey 2025.
What is a VCC and why was it created?
The VCC is a corporate form under Singapore law, sitting alongside the private limited company but with rules tailored to collective investment. Before 2020, a Singapore fund had to be structured as a company, a unit trust or a limited partnership — none of which mapped cleanly onto how funds actually operate. Managers who wanted segregated cells, variable capital and redemption-at-NAV typically went offshore, most often to the Cayman Islands. The VCC was MAS and ACRA's answer: an onshore vehicle that does what an offshore fund vehicle does, while providing a Singapore corporate domicile subject to the applicable regulatory and tax conditions. It can be used for both open-ended and closed-end strategies — hedge funds, private equity, venture capital, real estate, private credit and family office portfolios.
How is a VCC different from a private limited company?
The differences are structural, not cosmetic. A VCC's paid-up capital always equals its net asset value, so subscriptions and redemptions move capital up and down without the solvency machinery a Pte Ltd needs for a capital reduction. A VCC can pay dividends out of capital, not just profits. Its register of members is not open to the public, which matters to investors who value privacy. And critically, a VCC can be an umbrella holding many ring-fenced sub-funds — something a Pte Ltd cannot do. The trade-off is that a VCC may only be used as an investment fund and must appoint a regulated fund manager. We cover the full comparison in VCC vs Private Limited Company.
| Feature | VCC | Private Limited Company (Pte Ltd) |
|---|---|---|
| Purpose | Investment fund only | Any business |
| Capital | Variable; always equals NAV | Fixed; capital reduction needs solvency process |
| Sub-funds | Yes — ring-fenced under Section 29 | No |
| Dividends | May be paid out of capital | Only out of profits |
| Register of members | Not public | Public at ACRA |
| Fund manager | Mandatory MAS-regulated manager | Not required |
| Audit exemption | None — must be audited | Small companies may be exempt |
What is the difference between an umbrella VCC and a standalone VCC?
A standalone VCC holds a single pool of assets — one strategy, one set of investors. An umbrella VCC holds multiple sub-funds under one legal entity, each operating like its own fund with separate assets, investors, strategy and NAV. An umbrella can share governance and service arrangements, but the costs and operating terms depend on the mandate and providers. The segregation is statutory: under Section 29 of the VCC Act, the assets and liabilities of each sub-fund are segregated, so a creditor of Sub-Fund A cannot reach the assets of Sub-Fund B. We go deep on this in Umbrella VCC, sub-funds and ring-fencing.
| Feature | Umbrella VCC | Standalone VCC |
|---|---|---|
| Structure | One legal entity holding multiple sub-funds | One legal entity, one pool of assets |
| Asset segregation | Each sub-fund ring-fenced under Section 29 | Single pool — no internal ring-fencing needed |
| Adding a new strategy | Register a sub-fund under the existing VCC | Incorporate a separate VCC each time |
| Shared overhead | One board, secretary, auditor and admin across sub-funds | Dedicated to the single fund |
| Best for | Managers running several strategies or client mandates | A single fund or first launch |
| Tax incentive | Can be applied at umbrella level and flow to sub-funds | Applied to the one fund |
How does capital flow in and out of a VCC?
Because a VCC's capital is variable, investors subscribe and redeem at net asset value (NAV) without the legal friction an ordinary company faces. When an investor subscribes, the VCC issues new shares at NAV per share; when they exit, the VCC redeems shares at NAV and returns capital. A VCC may also pay dividends out of capital, which lets income strategies distribute without being trapped by a profits test. This is what makes the VCC behave like a fund rather than a holding company. The full mechanics — issuance, redemption, suspension and dividends — are in VCC shares, redemption and dividends at NAV.
Who governs a VCC — directors, secretary and auditor?
A VCC must have at least one Singapore-resident director and at least one director who is also a director or qualified representative of its fund manager (the same person can satisfy both). For an authorised scheme offered to retail investors, the requirements step up — at least three directors including one independent director, an approved trustee as custodian, and a registered prospectus. A VCC must appoint a company secretary within six months of incorporation and an auditor within three months, hold its AGM and file its annual return within set periods of its financial year-end, and — unlike a small Pte Ltd — it has no audit exemption. MAS set out its governance expectations in Circular IID 04/2025 (26 June 2025). Full detail in VCC governance, directors and corporate secretary.
Do I need my own fund manager licence to run a VCC?
A sponsor may appoint an existing permissible fund manager instead of establishing its own licensed entity. Eligible managers include licensed fund managers and specified exempt financial institutions; an SFO’s general exemption is not sufficient by itself. The manager must perform substantive fund management, and any advisory or sub-management role needs its own authorisation assessment. See appointing an existing manager and the fund management licensing guide.
Can I move an existing offshore fund into a VCC?
Yes. The VCC framework includes an inward re-domiciliation regime that lets a comparable foreign corporate fund — for example a Cayman company or segregated portfolio company — transfer its registration to Singapore as a VCC without creating a new legal entity. Legal continuity does not settle counterparty consents, banking, custody, investor documents or recognition of historical performance; review those separately. See VCC re-domiciliation and inward transfer and, for the offshore comparison, VCC vs Cayman SPC.
How do tax incentives sit on top of the VCC?
A VCC is a structure; tax exemption is separate and optional. Most managers pair a VCC with a fund tax incentive — Section 13O or Section 13U — administered with MAS, which exempts qualifying fund income from Singapore tax when conditions on AUM, investment professionals and local business spending are met. Importantly, a VCC umbrella can apply for an incentive at the umbrella level and have it flow to its sub-funds. The detail lives in the tax pillar: start with Singapore fund tax incentives and 13O vs 13U: which do I qualify for?
Discuss a VCC structure
Outline your strategy, investor requirements and timetable. We can introduce a licensed fund manager or relevant service provider to assess the proposed structure.
Discuss your requirements →How much does a VCC cost and how long does setup take?
Costs vary with whether you use your own licence or a hosted manager, single vs umbrella, and your service-provider mix (administrator, custodian, auditor, tax). Compare the two routes against the actual manager appointment, provider scope and timeline; incorporation is only one part of launch. The full breakdown of steps, timeline and fees is in Setting up a VCC: process and requirements.
Frequently asked questions
What is a VCC in Singapore?
A Variable Capital Company (VCC) is a corporate fund vehicle introduced under the Variable Capital Companies Act 2018 (in force 14 January 2020). It can hold one or many ring-fenced sub-funds, issue and redeem shares at net asset value, and pay dividends out of capital — features built specifically for investment funds rather than ordinary trading companies.
Is a VCC a fund manager licence?
No. A VCC is a fund vehicle, not a licence. Every VCC must appoint a Permissible Fund Manager that is licensed or regulated by the Monetary Authority of Singapore (MAS), or qualify under an exemption. The vehicle and the manager are two separate things.
How many VCCs have been set up?
1,406 VCCs had been incorporated or re-domiciled in Singapore by end-2025 (MAS Asset Management Survey 2025), holding several thousand sub-funds between them. Adoption has been led by hedge funds, private equity, family offices and external asset managers.
What is the difference between an umbrella VCC and a standalone VCC?
A standalone VCC holds a single pool of assets. An umbrella VCC holds multiple sub-funds under one legal entity, each ring-fenced under Section 29 of the VCC Act so that the assets and liabilities of one sub-fund cannot be used to meet the liabilities of another.
VCC Singapore is an independent informational resource and is not a regulator, law firm or tax adviser. The VCC framework is governed by ACRA and MAS and changes periodically — confirm current rules before acting. This page is general information, not legal, tax or financial advice.