
Fund management licensing in Singapore: CMS, LFMC and VCFM
Licensing categories, capital, staffing and the alternatives available to a sponsor appointing a fund manager.
A fund management licence in Singapore is the authorisation from the Monetary Authority of Singapore (MAS) that lets a company manage investment funds for clients. The main licence is the Capital Markets Services (CMS) licence for fund management, held by a Licensed Fund Management Company (LFMC). Venture capital managers can apply under the simplified Venture Capital Fund Manager (VCFM) licensing regime. The older Registered Fund Management Company (RFMC) regime was repealed on 1 August 2024.
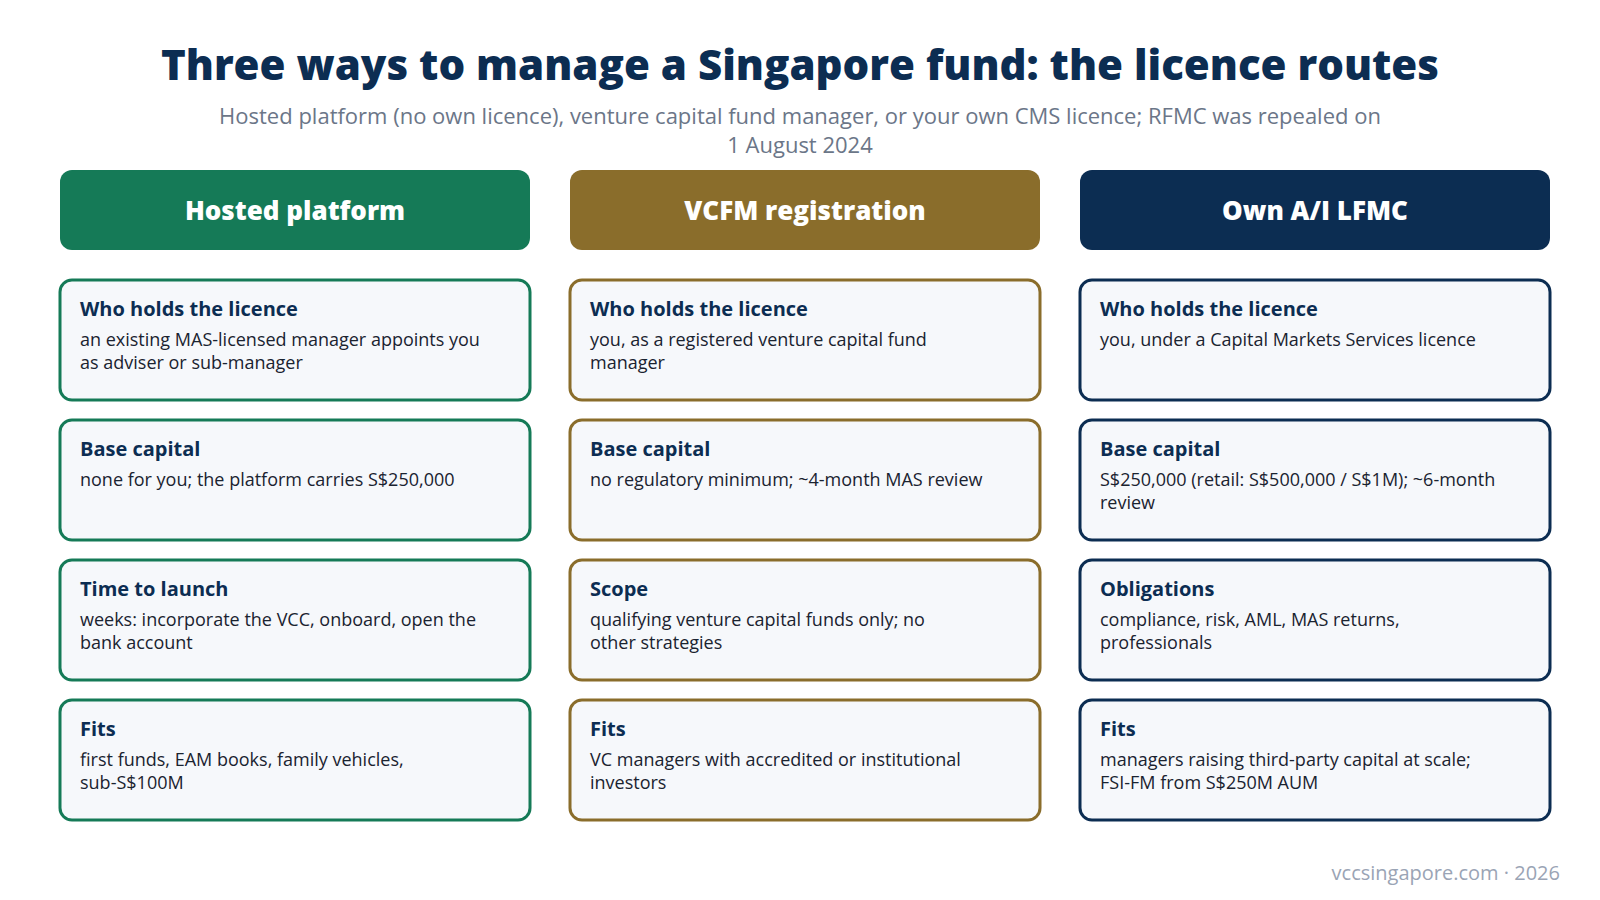
Crucially, a licence is something the manager holds — not the fund. A VCC is a vehicle, not a licence; it must appoint a licensed manager (a "Permissible Fund Manager"), but that manager can be your own company or an existing one. If your goal is simply to launch a fund quickly, read can you run a VCC without your own licence? first.
Update — 19 August 2026: the economics of holding a Singapore licence just improved. MAS announced a tax exemption on a share of the performance profits fund managers and investment professionals earn in qualifying funds (from 2026 income, details at Budget 2027), alongside wider ONE Pass visa access for senior investment hires. Full breakdown here.
Licensing for the proposed fund management activity
A company carrying on fund management generally requires a CMS licence unless a specific exemption applies. The VCFM regime is a simplified CMS licensing category, not an exemption from licensing. Assess the proposed investor base and activities to determine the appropriate category.
LFMC Singapore: Licensed Fund Management Company tiers
An LFMC holds a CMS licence for fund management. The accredited/institutional and retail categories differ according to the investors served; qualifying venture-capital activities have a distinct framework. Assess both the investor base and the planned activities before choosing a route.
The two LFMC tiers and the VCFM track
An A/I LFMC serves accredited and institutional investors only; a Retail LFMC may additionally serve retail investors and carries a higher bar. The VCFM is a simplified licensing regime confined to qualifying venture capital funds. The table below sets the three side by side.
| Licence | Who it serves | Base capital | SG-based pros | MAS review |
|---|---|---|---|---|
| A/I LFMC (CMS) | Accredited & institutional investors only | S$250k | ≥2 | ~6 months |
| Retail LFMC (CMS) | Retail + accredited + institutional | S$500k (S$1m if retail CIS) | ≥2 | ~6 months+ |
| VCFM | VC funds (qualifying criteria) | No regulatory minimum | ≥2 | ~4 months |
| RFMC | Repealed 1 August 2024 — transitioned to A/I LFMC via Form 1AR | |||
What is an A/I LFMC?
The Accredited/Institutional LFMC is the workhorse licence for boutique and mid-sized managers. It may serve only accredited investors (high-net-worth individuals and entities meeting MAS wealth/income thresholds) and institutional investors. It carries a S$250k base capital requirement and must maintain risk-based capital of at least 120%. Following the RFMC repeal, the old S$250 million AUM cap that limited smaller managers is gone — an A/I LFMC can now scale AUM without an upper bound. For the build-out process, see setting up your own independent asset manager.
What is a Retail LFMC?
A Retail LFMC may additionally serve retail investors. Because retail money carries more protection obligations, the bar is higher: S$500k base capital (rising to S$1m where the manager runs a retail collective investment scheme), more demanding compliance, audit and disclosure requirements, and a track record expectation. Most new boutiques start as A/I and only move to retail when a genuine retail product justifies it.
What is a VCFM and when does it fit?
The Venture Capital Fund Manager regime is a simplified licensing process for managers of qualifying VC funds. It has no regulatory minimum base capital and a faster MAS review (around four months), reflecting that VC funds invest in illiquid, non-retail businesses. The trade-off is scope: VCFMs are confined to qualifying VC funds and cannot freely pivot to liquid or retail strategies. The detail — including how the RFMC repeal interacts with VCFM — is on VCFM & the RFMC repeal.
What happened to the RFMC regime?
The Registered Fund Management Company was a lighter-touch registration capped at S$250m AUM and 30 qualified investors. MAS repealed it on 1 August 2024, transitioning existing RFMCs to A/I LFMC status through a streamlined Form 1AR process and removing the AUM cap in the process. New managers can no longer register as an RFMC — the entry point for accredited/institutional managers is now the A/I LFMC. Anyone reading a guide that still presents the RFMC as a live option is reading pre-August-2024 information.
Requirements to assess for the selected category
- At least two Singapore-based professionals — typically a CEO/director and a representative, resident in Singapore.
- Fit-and-proper directors, shareholders and representatives.
- Applicable capital requirements. Assess the base-capital floor and risk-based requirement for the category; the VCFM regime is excluded from the Part III financial-resources requirement.
- A compliance function, independent audit, professional indemnity insurance and proper risk management.
- A physical Singapore office and genuine substance — MAS expects the manager to be run from Singapore.
What are the LFMC application and annual fees?
Application and recurring licence fees are separate from the capital and operating resources the firm must maintain. The indicative amounts below should be confirmed with MAS before applying.
| Fee | Indicative amount | Notes |
|---|---|---|
| CMS licence application fee | ~S$1,000 | Non-refundable, paid with the Form 1 application per regulated activity |
| Representative lodgement fee | ~S$200 per representative | Per appointed representative notified/lodged with MAS |
| Annual licence fee | ~S$2,000-8,000 | Recurring, scaling with the regulated activities and the company's scope |
| Base capital (for context) | S$250k (A/I) · S$500k-1m (Retail) | Held, not a fee — plus risk-based capital of at least 120% |
Budget for staffing, premises, systems, compliance, audit and insurance alongside licence fees and capital. Compare those continuing commitments with the proposed fees and scope of an existing fund manager.
Establishing a licensed firm or appointing a manager
Establishing a licensed firm requires capital, staff and continuing regulatory oversight. Alternatively, a VCC can appoint an existing permissible fund manager. The appointment does not transfer the licence to the sponsor; assess any advisory role against the activities performed. Compare responsibilities and fees in the appointed-manager model.
Establish your fund management framework.
Describe your strategy, investor base and proposed management arrangements to request an appropriate specialist introduction.
Discuss your requirements →How licensing connects to the rest of your setup
The licence sits underneath the VCC vehicle and is one of the four building blocks in how to start a fund in Singapore. Once the manager is sorted, most funds layer on a 13O or 13U tax incentive and appoint their service providers. External asset managers often use this licensing decision as the bridge from advising to managing — see from EAM to licensed fund manager.
Frequently asked questions
What licence do you need to manage a fund in Singapore?
To carry on fund management you generally need a Capital Markets Services (CMS) licence for fund management from MAS, held by a Licensed Fund Management Company (LFMC). Venture capital managers can instead apply for a CMS licence under the Venture Capital Fund Manager (VCFM) regime. The older RFMC regime was repealed on 1 August 2024.
What is the difference between an A/I LFMC and a Retail LFMC?
An A/I LFMC may only serve accredited and institutional investors and carries a base capital requirement of S$250k. A Retail LFMC may also serve retail investors and carries a higher base capital requirement of S$500k (S$1m where it manages a retail collective investment scheme), plus heavier compliance obligations.
Was the RFMC regime abolished?
Yes. MAS repealed the RFMC regime on 1 August 2024. Existing RFMCs were transitioned to A/I LFMC status via a streamlined Form 1AR process, removing the old S$250 million AUM cap that applied to RFMCs.
Do I need my own licence to launch a VCC?
A VCC can appoint an existing permissible fund manager. This may avoid establishing a separate licensed management company, but it does not transfer the manager’s licence to the sponsor. Assess the sponsor’s own activities and the terms of the management appointment.
VCC Singapore is an independent informational resource and is not a regulator, law firm or tax adviser. Licensing tiers, capital and headcount requirements are set by MAS and change periodically — confirm the current figures before acting. This page is general information, not legal, tax or financial advice.